How it works
One daily calculation, from your transactions
Most attribution is monthly and based on holdings. That misses intra-month trades, corporate actions and cash that sat uninvested for part of the month.
Daily, from the trades
Returns compound the way the portfolio actually behaved, and each effect traces back to a trade.
No residual
The effects come out of the return calculation, so they add up exactly to the active return.
Your own numbers
Your prices, classifications, durations and yields, so exposures match what PMs already quote.
The attribution screen
Sector by sector, stock by stock
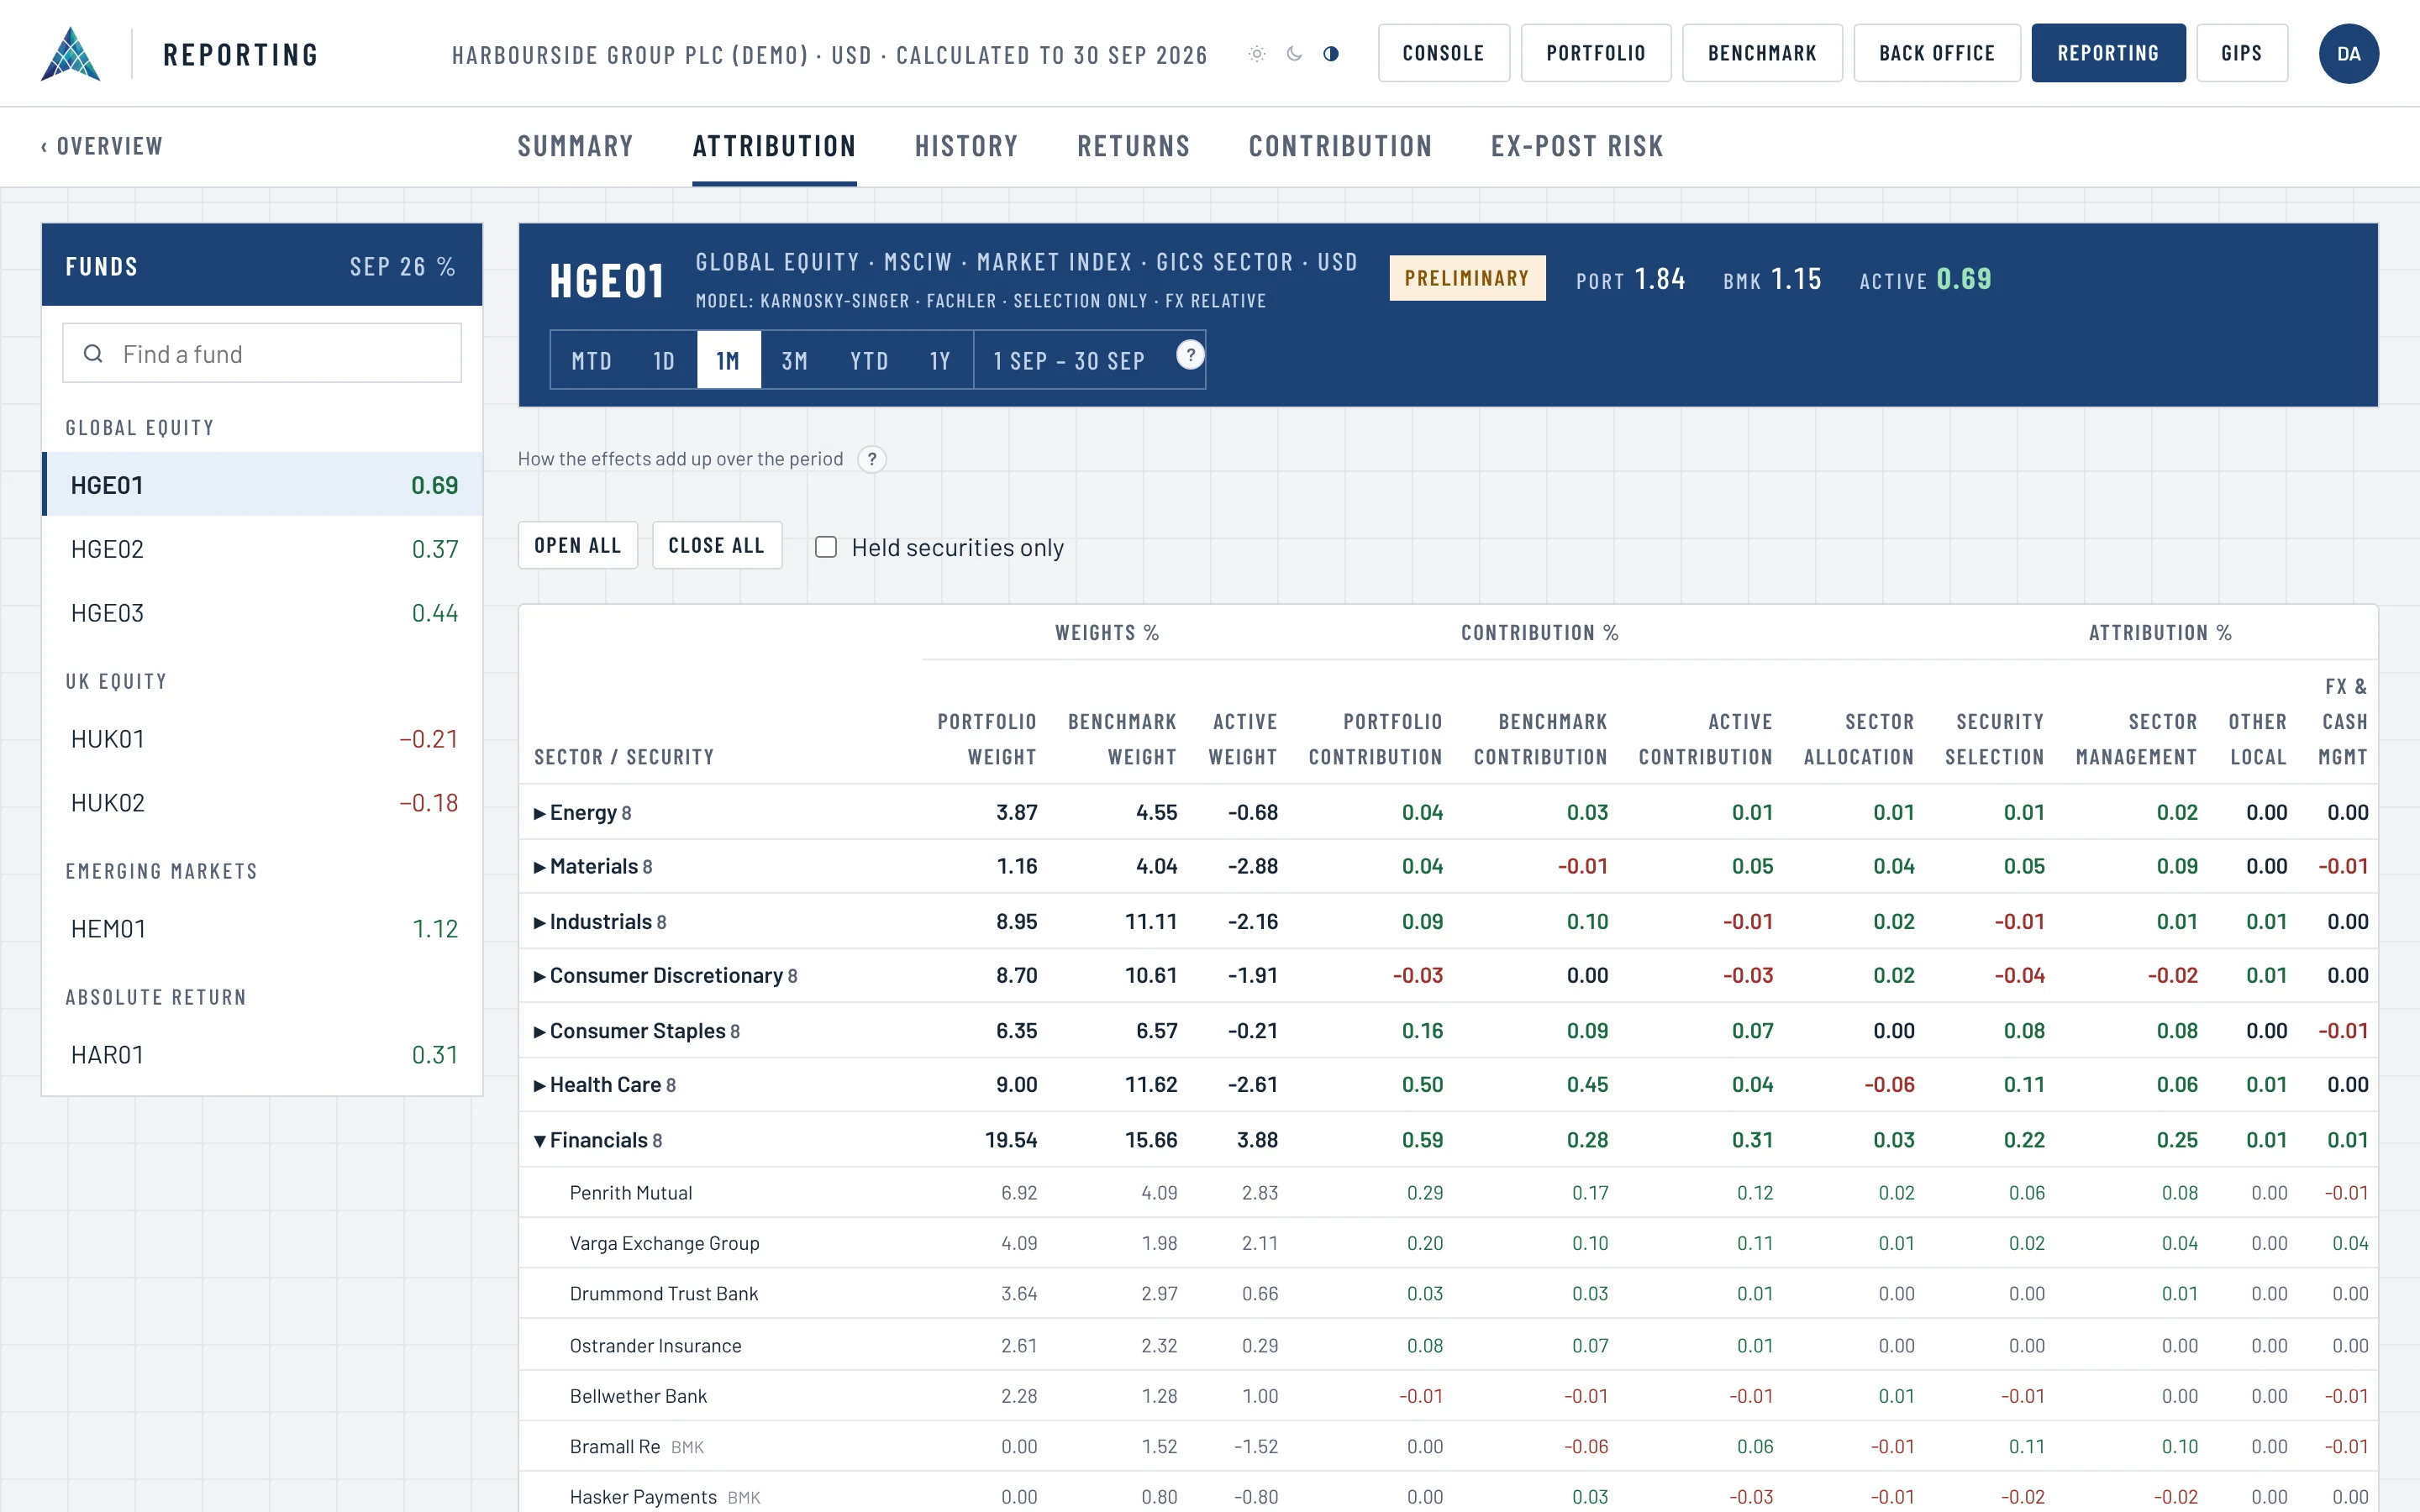
Demonstration fund HGE01, September 2026.
1
Every sector on one line
Weights, contributions and effects for every sector, for the fund and its benchmark, adding across to the active return.
2
Open a sector to see its stocks
Financials is open here. Benchmark names the fund does not hold are marked BMK, so an underweight is as visible as a holding.
3
Your own sectors
This fund uses GICS sectors. It can be any scheme you already maintain: sector, desk, strategy, rating band or duration bucket.
Models
Brinson-Fachler, Brinson-Hood-Beebower and Karnosky-Singer for equity and multi-asset; modified van Breukelen for fixed income. GIPS composites are included.
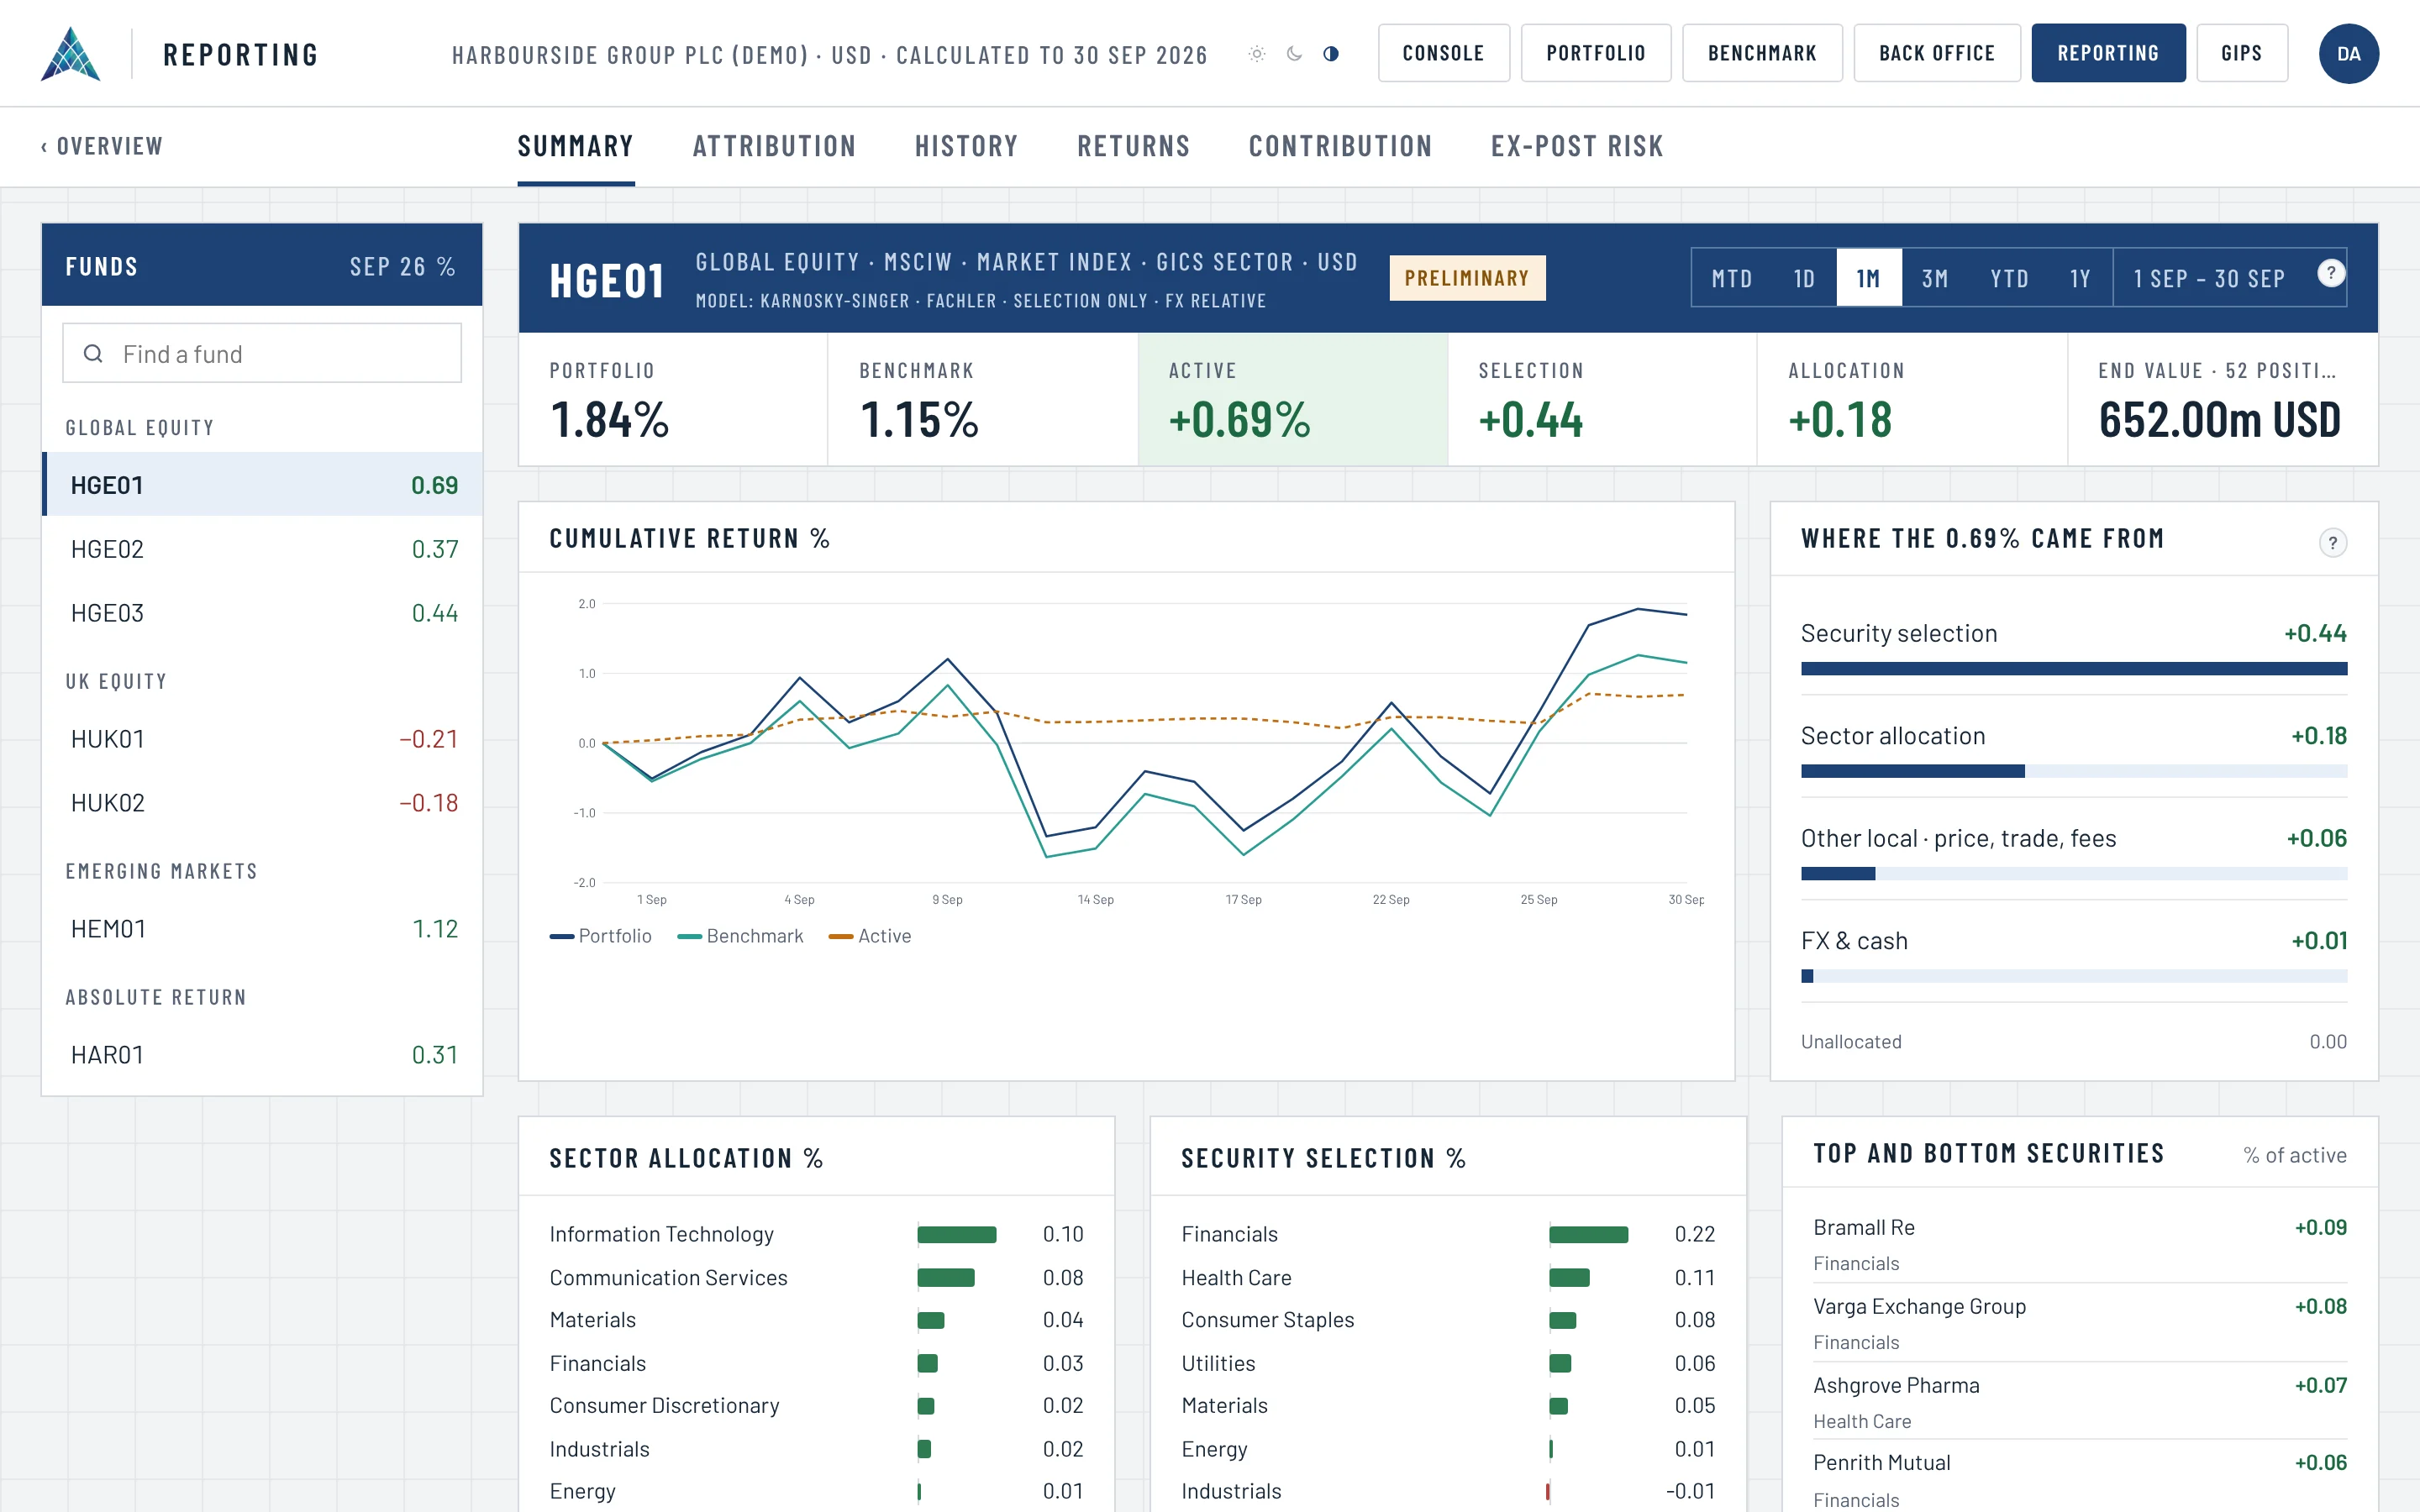
Where the 0.69% came from
Stock selection added 0.44, sector allocation 0.18, trading 0.06 and FX and cash 0.01. Together they make the whole 0.69%, with nothing unallocated.
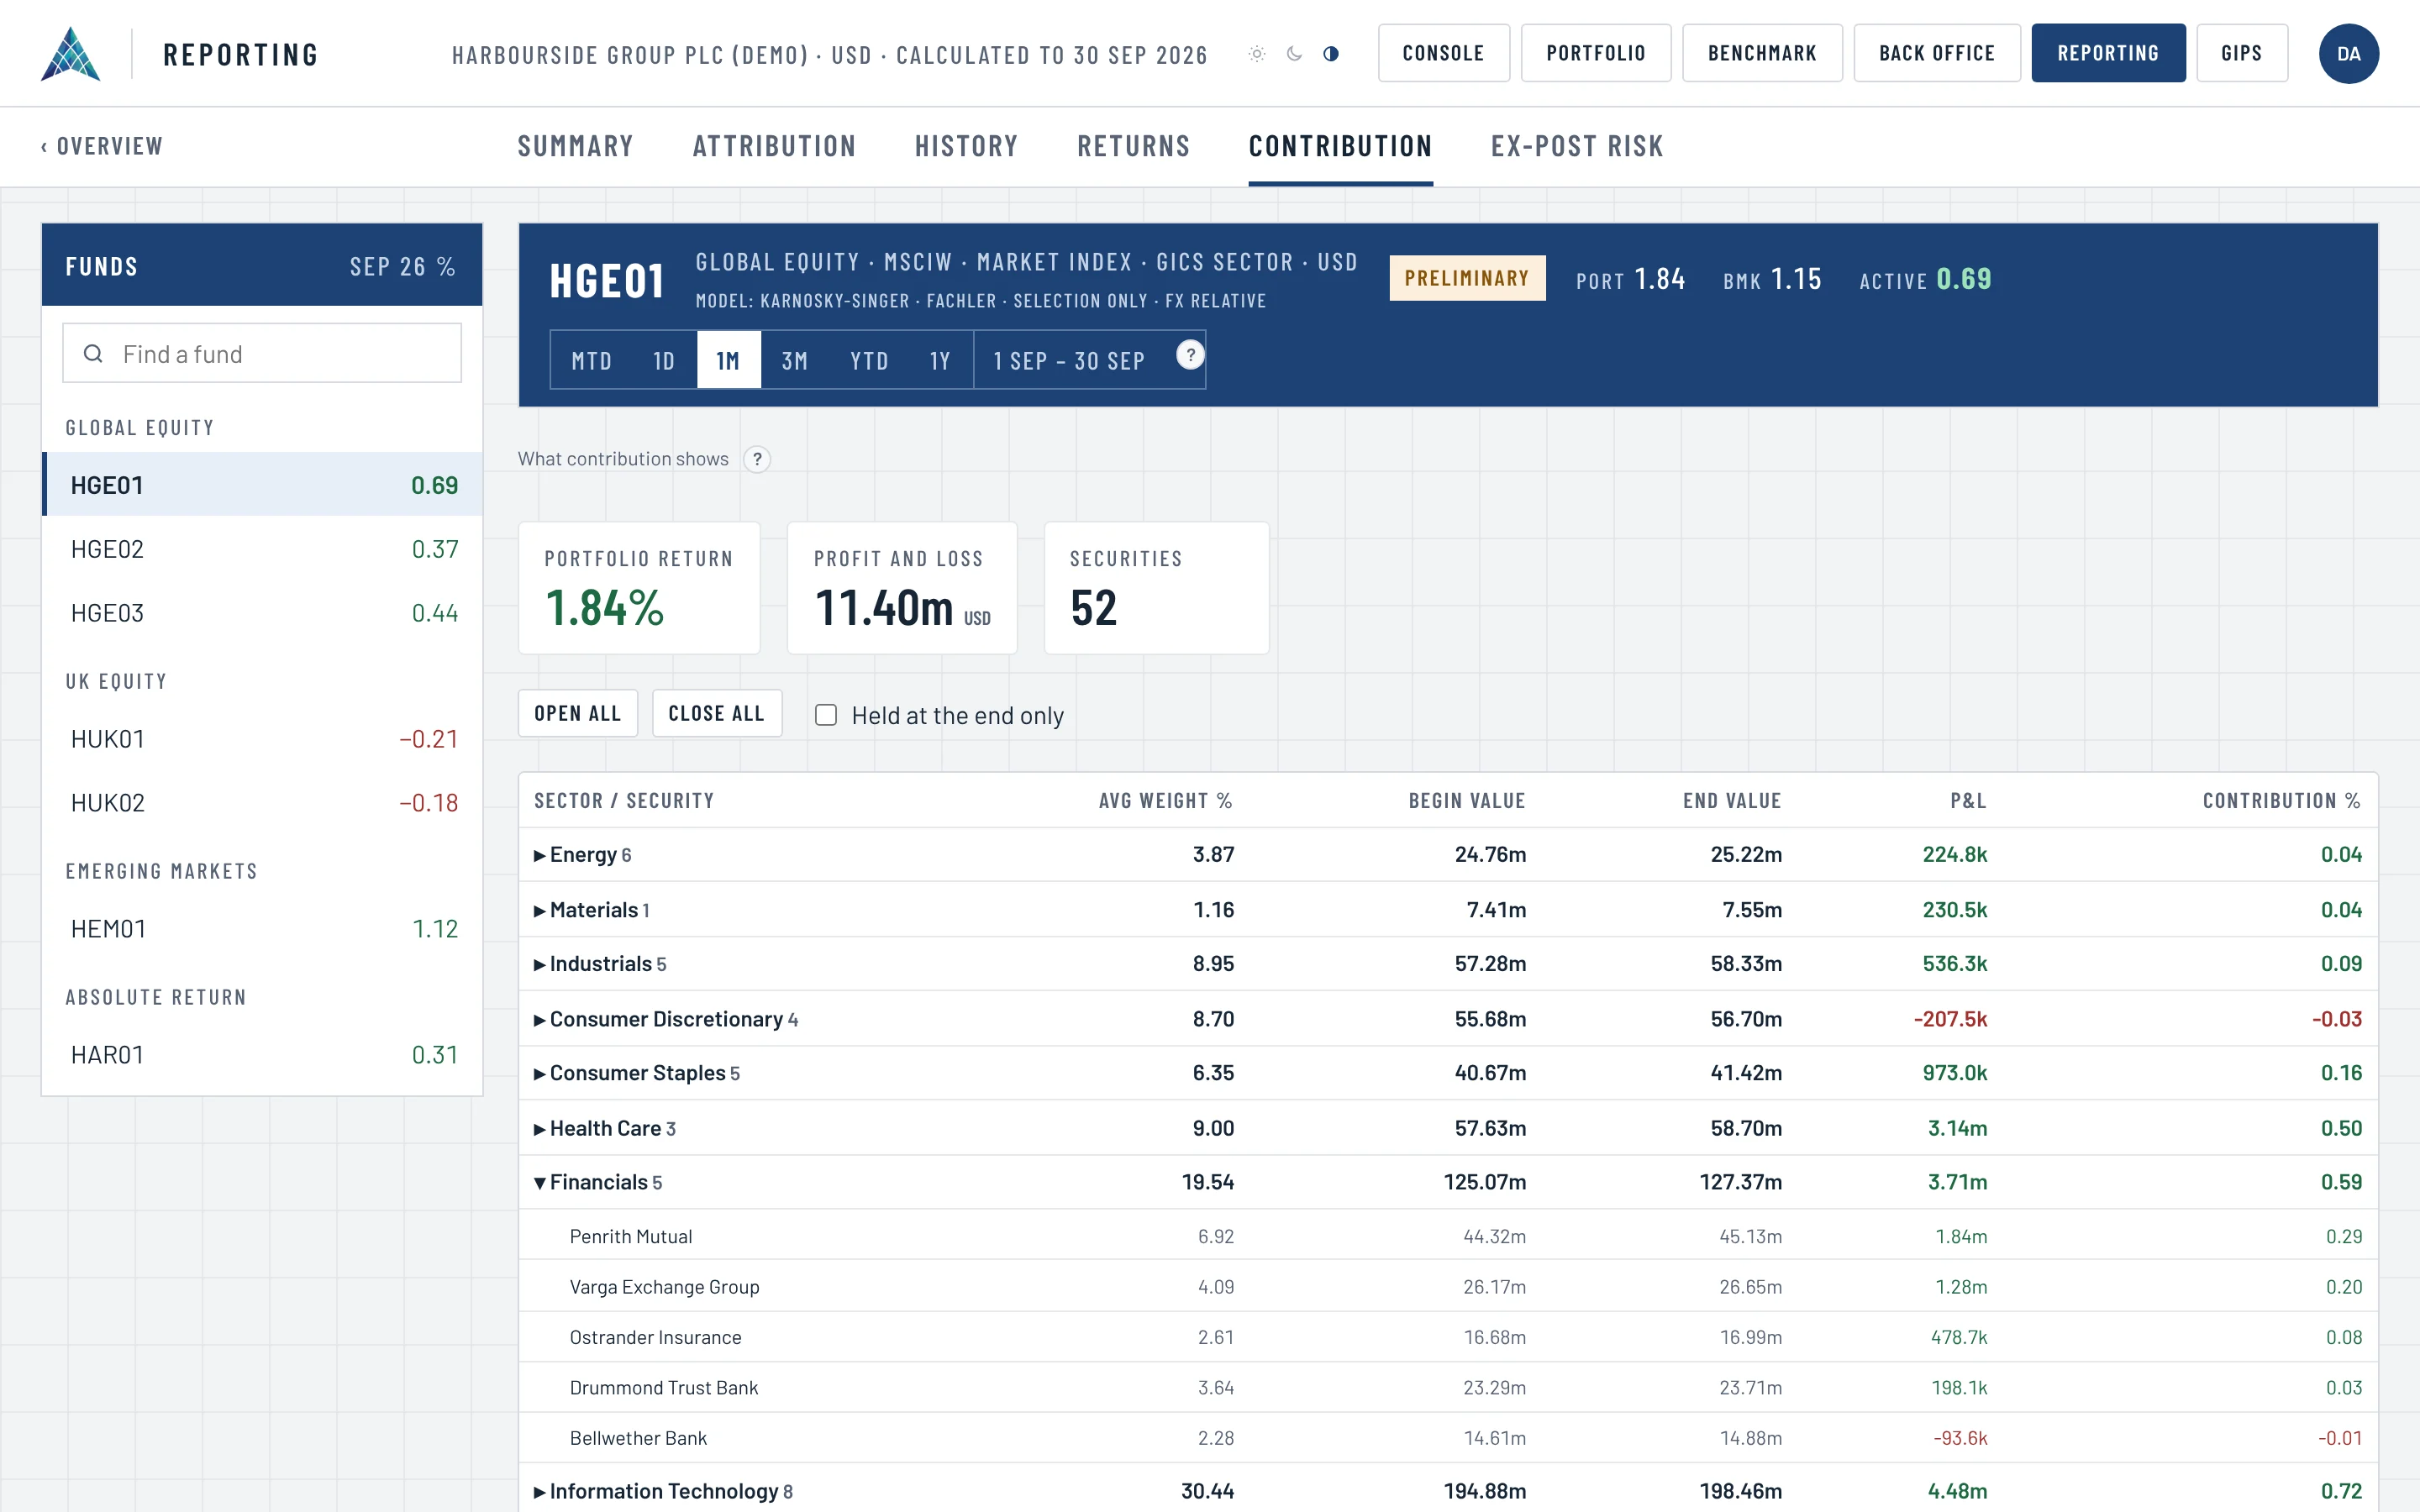
What each holding contributed
Each stock's share of the 1.84% return, with its average weight, value and profit over the period. Click a stock to see it day by day.
See the rest of the screens
The tour walks through a performance team's day, a portfolio manager's view and client reporting with GIPS.